The End of Arbitrary Punitive Garnishee Orders by KRA
Key Insights
Before an agency notice can be lawfully issued:
- KRA must issue a formal tax assessment.
- The taxpayer must be given a fair opportunity to respond, explain variances, and lodge a formal objection.
- The tax debt must be firmly crystallized (i.e., undisputed or the appeals process must have been fully exhausted).
Operating a business in Kenya is a toll-order. Furthermore, in addition to dealing with the uncertainty of the market and unscrupulous competitors, business have to deal with an amorphous regulatory environment that is constantly morphing and highly complex to adhere to. The most notoriously unclear of these regulation has been the Garnishee orders from KRA. For years, many Kenyan businesses have woken up to the reality of frozen bank accounts, paralyzed operations, and blocked funds due to abrupt "Agency Notices" issued by the Kenya Revenue Authority. These notices act as statutory garnishee orders, directing banks to forcefully remit a taxpayer's funds to the taxman to settle alleged tax arrears.
NOT ANYMORE. In a series of defining judgments, the High Court of Kenya in Katahira & Engineers International Limited v Kenya Revenue Authority [2026] directed that KRA can no longer use agency notices as aggressive, first-resort weapons to instruct banks to forcefully remit a taxpayer's funds to the taxman without strictly adhering to due process. Under Section 42 of the Tax Procedures Act (TPA), KRA has the power to appoint a third party (usually a taxpayer's bank, employer, or debtor) as a tax agent. Once the notice is issued, the bank has a legal obligation to freeze the affected accounts and remit the specified funds to KRA.
While this is a legitimate debt recovery tool, the High Court has noted that KRA often misused it prematurely to coerce taxpayers, bypassing standard assessment and objection procedures. To the COURT, Due Process is Not a Suggestion; It is a Constitutional Right.
Justice RE Aburili observed that KRA is bound by Article 47 of the Constitution of Kenya, which guarantees every person the right to fair administrative action that is expeditious, efficient, lawful, reasonable, and procedurally fair. In layman’s terms, the Court was of the opinion that KRA cannot ambush a taxpayer. Before an agency notice can be lawfully issued:
- KRA must issue a formal tax assessment.
- The taxpayer must be given a fair opportunity to respond, explain variances, and lodge a formal objection.
- The tax debt must be firmly crystallized (i.e., undisputed or the appeals process must have been fully exhausted).
Issuing a garnishee order while a taxpayer still has a pending, valid objection or appeal is considered ultra vires (acting beyond legal power) and an abuse of administrative justice.
Before this rulling, KRA could decide a taxpayer is guilty of tax evasion, assess a random figure, and freeze their accounts without seeking the taxpayer's version of events or reviewing their supplied documents. This was a direct violation of the principle of audi alteram partem (listen to the other side). As a taxpayers, the take way from this landmark rulling is that when KRA acts as the investigator, judge, and executioner all at once, the courts will step in to quash those notices via orders of Certiorari.
Rocket bookkeepers is here to keep you updated on matters business operations.
- Know Your Rights: If KRA issues an agency notice without a prior assessment, or while you have a valid objection filed within the 30-day statutory window, you have grounds to seek relief from the High Court.
- Do Not Ignore KRA Letters: The protection of due process only applies if you actively engage. If KRA sends an assessment and you fail to object within 30 days, the tax becomes undisputed, and KRA is legally justified in issuing an agency notice.
- The Courts Will Intervene: Taxpayers no longer have to succumb to procedural impropriety. If KRA bypasses the Fair Administrative Action Act, the High Court has shown it will not hesitate to lift the agency notices and compel the Authority to follow the law.
Remember, taxes are the lifeblood of any nation, and KRA has a legal mandate to collect them. Neverthless, tax collection must be anchored in the rule of law, transparency, and procedural fairness. The era of shoot-first-ask-questions-later tax enforcement is over.
"Justice R.E. Aburili stated, "There was no evidence adduced by KRA to demonstrate that the said amounts had been assessed and were due for payment or that demand was ever made to Kahathira & Engineers International Ltd and they declined to settle""
Disclaimer: This article is for informational purposes only and does not constitute legal or financial advice. Always consult with a certified tax consultant or an Advocate of the High Court of Kenya regarding specific tax disputes.
Related News & Updates
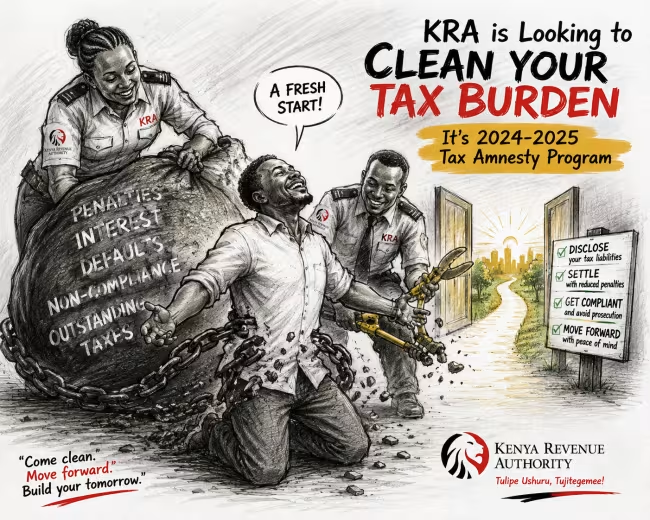
The Tax Procedures (Amendment) Act, 2024 introduces a tax amnesty on interest, penalties, and fines for unpaid taxes accrued up to December 31, 2023.
Before an agency notice can be lawfully issued:
Our Strategic Partners
We are proud to collaborate with organizations that share our commitment to professional integrity and operational excellence.